Learn how to use a mortgage calculator to estimate payments, compare scenarios, include ownership costs, and set a realistic Canadian home budget.
A mortgage calculator can estimate a monthly payment, but it cannot tell you whether a home is safely affordable or whether a lender will approve your application. For buyers in Mississauga and the broader GTA, the better question is: what total housing cost can you manage while leaving room for other priorities and unexpected expenses?
This mortgage calculator guide explains the key inputs, limitations and next steps. You will learn how to turn a payment estimate into a practical budget for comparing homes, condos and investment properties.
Quick summary

What a mortgage calculator actually tells you
A mortgage calculator estimates a loan payment and repayment schedule from the information you enter. The Government of Canada’s mortgage calculator can also illustrate payment schedules and the potential effect of prepayments.
This is useful for comparing a different purchase price, down payment or amortization before you review listings. However, the result is not mortgage approval, a guaranteed rate, a maximum borrowing limit or a complete affordability assessment.
The estimate may exclude taxes, insurance, utilities, maintenance, condo fees and other debts. A lender will assess your income, expenses, credit history, documentation and applicable criteria. A real estate professional can help compare properties, but financing approval belongs with the appropriate lender or mortgage professional.
The main inputs: price, down payment, rate and amortization

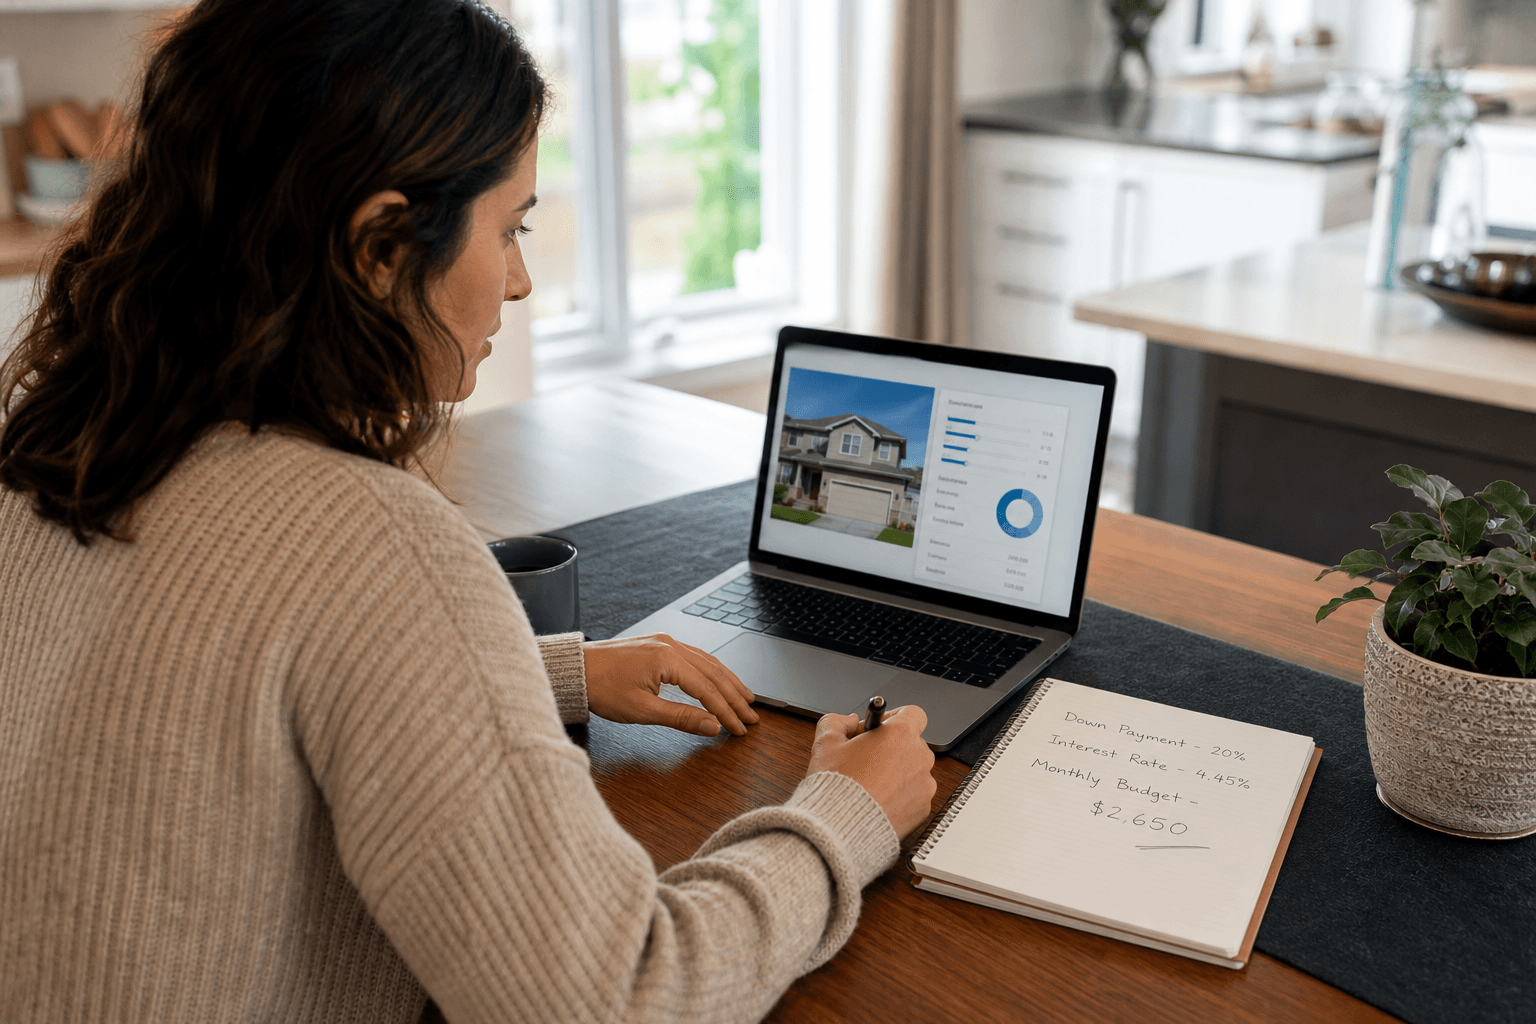
Enter figures consistently and record the date and source of any interest rate used. Update the estimate when the assumptions change.
Purchase price and mortgage amount
The purchase price is what you may pay for the property. The mortgage amount is generally the portion financed after the down payment and applicable adjustments. Some calculators ask for the price, while others ask directly for the loan amount, so confirm which figure the tool expects.
Down payment
A larger down payment usually reduces the amount borrowed, but do not commit every available dollar. You may need cash for closing costs, moving, immediate repairs and emergency reserves. Mortgage insurance and other financing details can also depend on the relationship between price and down payment.
Interest rate
The rate directly affects the payment estimate and interest cost. An advertised rate, an old pre-approval or a general online example may not apply to your circumstances. Test a less favourable rate instead of building the entire budget around the lowest assumption.
Amortization and mortgage term
The amortization period is the time used to plan repayment of the mortgage in full. A longer amortization can reduce scheduled payments but generally extends the period over which interest is paid. A shorter amortization can increase payments while shortening repayment.
Do not confuse amortization with the mortgage term. The Financial Consumer Agency of Canada explains the difference in its mortgage terms and amortization guidance.
Payment frequency
Monthly, accelerated and other payment schedules produce different payment amounts and repayment patterns. Choose the frequency that reflects your intended plan, then confirm the lender’s calculation.
A hypothetical mortgage calculator example
Suppose a buyer enters these illustrative assumptions:
- Purchase price: $500,000
- Down payment: $100,000
- Mortgage amount: $400,000
- Interest rate: 5%, for illustration only
- Amortization: 25 years
- Payment frequency: monthly
A basic calculator would produce an estimated principal-and-interest payment of approximately $2,338 per month. This is not a quote, approval or recommendation. It only demonstrates how loan assumptions become a payment estimate.
The figure does not automatically include property taxes, home insurance, utilities, maintenance, condo fees, closing costs or moving expenses. Use examples to compare scenarios, not to decide that a particular property is affordable.
How each assumption changes the estimate
| Change | Likely payment effect | Tradeoff to review |
|---|---|---|
| Higher purchase price | Usually increases the amount borrowed and payment | Whether the added space or location justifies the total cost |
| Larger down payment | Usually reduces the amount borrowed and payment | Whether enough cash remains for closing and reserves |
| Higher interest rate | Usually increases payment and interest cost | Whether the budget works under less favourable financing |
| Shorter amortization | Usually increases the scheduled payment | Faster repayment versus less monthly flexibility |
| Longer amortization | Usually reduces the scheduled payment | Longer repayment and potentially higher total interest |
Run a base case, a cautious case and a case for a different property type or community. If the purchase works only under the most optimistic assumptions, revisit the budget.
Why the mortgage payment is only part of the budget
Ownership costs depend on the specific property. CMHC’s homebuying guidance encourages buyers to plan financing and understand inspections, appraisals, legal steps, realtors and lenders.
For a house, your monthly estimate may include:
- Mortgage principal and interest
- Property taxes
- Home insurance
- Utilities and internet
- Repairs and routine maintenance
- Emergency or replacement reserves
For a condo, add the applicable condominium fee and check what it covers. It does not eliminate the need to understand unit insurance, taxes, repairs and possible fee changes.
Also allow for legal services, inspections, adjustments, moving, furnishing and immediate repairs. The exact amount varies by transaction, so confirm relevant costs instead of relying on a generic percentage.
When comparing a condo with a house, compare the full ownership budget rather than the advertised price alone. This full condo versus house cost comparison can help organize the differences.
Mortgage calculator, affordability calculator or qualifier tool?
| Tool | Main question | Best use |
|---|---|---|
| Payment calculator | What might the payment be under these loan assumptions? | Compare price, down payment, rate and amortization |
| Affordability calculator | What home price may fit income, debts and expenses? | Build an initial price range |
| Qualifier tool | Could I qualify based on my financial information? | Prepare for a lender conversation |
CMHC provides home affordability, mortgage payment and insurance calculators. These remain estimates. A lender or mortgage professional must review your actual circumstances and current requirements.
How first-time buyers can turn an estimate into a search budget
- Separate available cash. Distinguish the down payment from money reserved for closing, moving, repairs and emergencies.
- Set a cautious payment range. Leave room for ordinary household expenses and future changes.
- Add property-specific costs. Include taxes, insurance, utilities, condo fees and maintenance.
- Test multiple scenarios. Compare a lower price, different down payment and higher rate.
- Discuss the inputs. Ask a lender or mortgage professional which figures require documentation.
- Search within the confirmed range. Compare actual properties by total monthly cost, location and condition.
Qasim Khan Real Estate presents its mortgage calculator as an initial planning tool for first-time buyers. A Milton home search can show how an estimate fits actual property types and availability, but a listing should not be treated as affordable until financing and the full budget are reviewed.
Use the result when comparing Mississauga and GTA properties
Apply the same worksheet to each property. Record asking price, down payment, mortgage amount, rate, amortization, payment, taxes, condo fees, insurance, utilities and known maintenance concerns.
Then compare commute, space, building condition, parking, transit, outdoor space and community priorities. A lower payment is not necessarily better if the property is a poor fit, while a higher payment needs a clear reason to stretch the budget.
For buyers comparing Mississauga, Milton and other GTA communities, keep financial assumptions consistent before changing location. A targeted property search in Mississauga can help connect your budget with practical viewing criteria.
For investors: add carrying costs, reserves and stress tests
An investor should not use a mortgage calculator to declare that a property will cash flow. The calculator estimates financing. It does not verify rent, vacancy, management costs, repairs, taxes, insurance, condo fees, financing conditions, resale value or tax treatment.
Define the objective, holding period, available cash, acceptable monthly shortfall and tolerance for uncertainty. Place the mortgage estimate beside all expected costs, labelling each income or expense assumption as verified, estimated or unknown.
- Test lower-than-expected income.
- Allow for vacancy or delayed occupancy.
- Model higher maintenance, insurance or condo costs.
- Test a less favourable renewal or rate assumption.
- Consider an exit later than planned.
For income-property buyers, an investment analysis checklist can place the payment beside financing requirements, reserves and due diligence. The result should be a decision to proceed, investigate or pause, not a promise of income or appreciation.
Mortgage calculator review checklist
- Is the purchase price and mortgage amount correct?
- Is the down payment source confirmed, with cash remaining for closing and reserves?
- Is the interest rate current, dated and appropriate for the scenario?
- Have you distinguished the mortgage term from amortization?
- Does payment frequency match your plan?
- Have you added taxes, insurance, utilities and maintenance?
- For a condo, have you confirmed the current fee and what it covers?
- Have you allowed for legal, inspection, moving and transaction costs?
- Would the budget work under less favourable assumptions?
- Has a lender or mortgage professional reviewed the information before an offer?
Mortgage calculator guide FAQ
Is a mortgage calculator the same as mortgage approval?
No. It produces an estimate. Approval requires review of your financial information, property and lender criteria.
What information do I need before using one?
Gather the price or mortgage amount, down payment, rate, amortization and payment frequency. Add taxes, insurance, utilities, condo fees, maintenance, closing costs and reserves for a more useful budget.
Should I calculate affordability using the price or mortgage amount?
Use both. The price describes the property, while the mortgage amount helps estimate financing after the down payment and applicable adjustments.
Does a mortgage calculator include taxes and condo fees?
Some tools allow additional costs, but a basic payment calculator may show only principal and interest. Check the tool and add missing costs separately.
When should I use a qualifier tool?
Use a payment calculator for scenarios and an affordability or qualifier tool when preparing for a lender discussion involving income, debts and expenses. Neither replaces lender review.
Can investors use one to determine cash flow?
No. It estimates financing only. Cash flow also depends on income, vacancy, operating costs, reserves, taxes and the exit plan.
Use the calculator as a starting point
A mortgage calculator is most useful when it helps you compare realistic scenarios. Enter clearly labelled assumptions, distinguish the payment from total ownership cost, and test changes to price, down payment, rate and amortization.
After expanding the estimate into a full budget and reviewing it with an appropriate mortgage professional, you can compare GTA properties by financial fit, location, condition and intended use.
For property comparisons, focused search guidance or a private consultation across Mississauga and the GTA, contact Qasim Khan Real Estate.
Written by
Qasim Khan
Real Estate Professional, QASIM KHAN Real Estate